


Counterpoint: Global DRAM revenue approaches $200 billion in Q3, up 369% year-on-year to achieve super cycle
According to the "Global Memory Market Tracker" report released by market research firm Counterpoint Research today, the global DRAM market revenue in the third quarter of 2026 was nearly $200 billion (note: the current exchange rate is about 1.34 trillion yuan), a year-on-year increase of 369%, nearly five times that of the same period last year.
Counterpoint Research points out that this round of DRAM market growth is mainly driven by price increases, rather than a significant increase in shipments. The unit shipment volume of DRAM increased by only about 4% compared to the previous quarter, and the average selling price per Gb reached $1.9.
Senior analyst Jeongku Choi stated that this round of market trend belongs to a price driven super cycle, rather than a shipment volume cycle. AI has transformed memory from a common commodity to a high-value scarce resource, and buyers' current core action is to compete for supply rather than negotiate. Against the backdrop of sustained price increases, storage vendors will set new profit records in the next quarter. ”
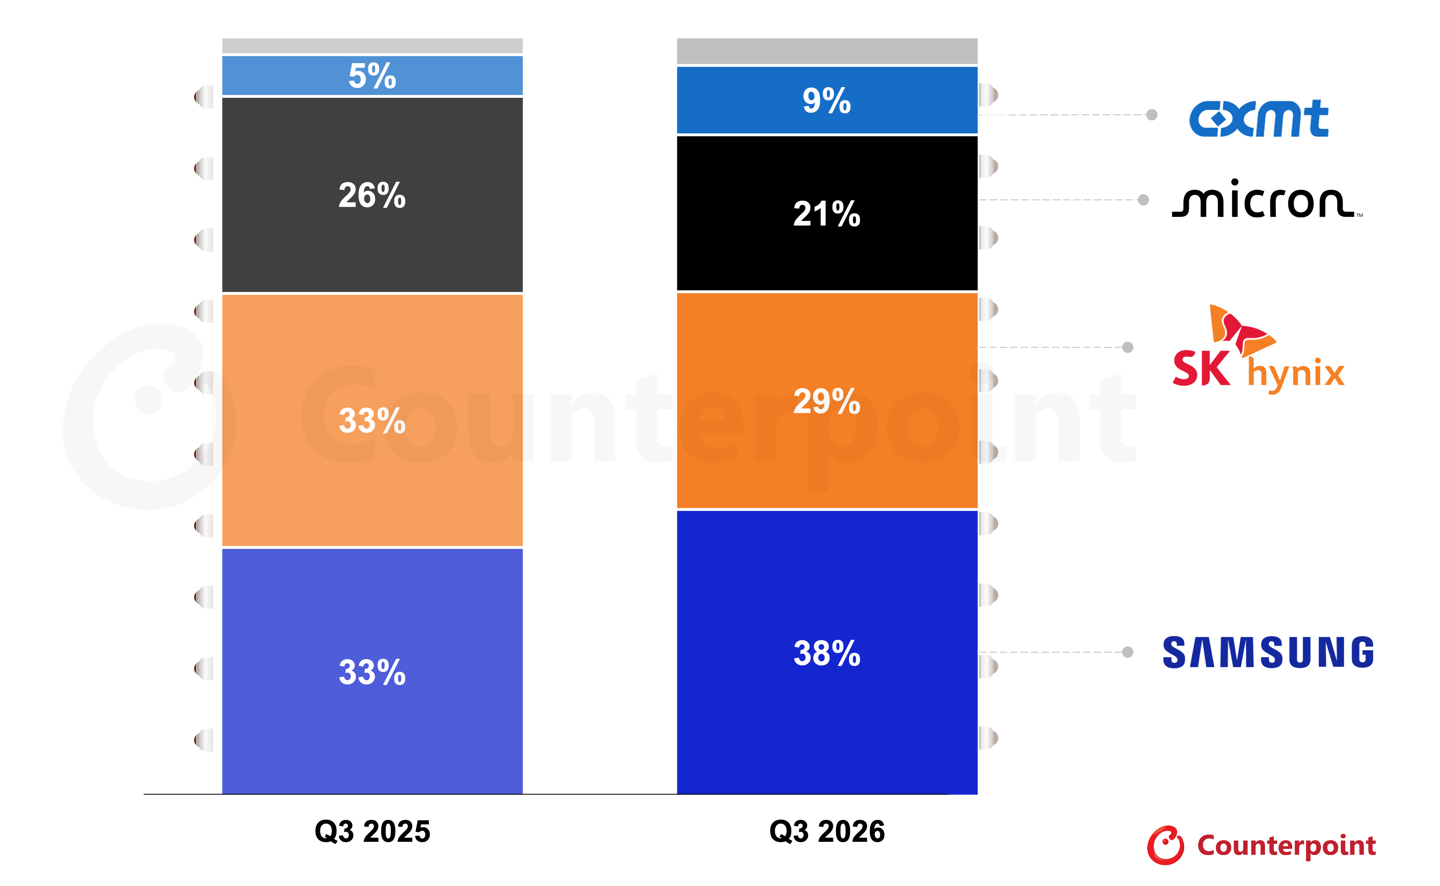
From the perspective of branch manufacturers, Samsung Electronics holds the top spot in the DRAM market with a market share of 38%; SK Hynix's month on month revenue growth exceeded 40%, significantly narrowing the gap with Samsung and recovering some market share lost earlier this year; Micron also performed strongly driven by the memory demand of AI data centers, but its growth rate lagged behind Samsung and SK Hynix; Changxin Storage's market share has declined from 10% in the second quarter to 9% in the third quarter. As competitors begin shipping HBM4 products with higher premiums from the fourth quarter, Changxin Storage's market share is expected to continue to be under pressure.
From the perspective of product structure, HBM's revenue has almost doubled, but its proportion in the total DRAM revenue has actually decreased, due to the faster growth of traditional DRAM products.
MS Hwang, Research Director at Counterpoint Research, stated that as the new generation of HBM products is gradually launched, the competitive landscape among manufacturers is also changing. SK Hynix previously held an advantage in the HBM3E market, while Samsung HBM4 received positive feedback from customers. He expects Samsung to become the manufacturer with the highest market share in HBM next year.
The growth in demand for traditional DRAM is also related to changes in AI infrastructure. Brady Wang, Deputy Director of Counterpoint Research, stated that AI agents are driving the growth in demand for traditional DRAM.
According to Counterpoint Research's cloud based AI computing power tracking data, the ratio of GPU to CPU has been reduced from 4:1 to 2:1 and is showing a further trend towards 1:1. Taking the NVIDIA Vera Rubin rack as an example, the DRAM capacity per CPU slot has increased to 1.5TB, nearly three times that of the previous generation product.
Brady Wang also pointed out that the average selling prices of DDR and LPDDR have both risen to historical highs, with related product revenue increasing by 500% and nearly 400% year-on-year, respectively. With the increase in server CPU usage, the demand for traditional DRAM is expected to continue to grow and may further push up the average selling price per Gb next year, while putting cost pressure on the edge device market.
MS Hwang also added, "Memory prices will remain strong next year, with HBM prices lagging behind General DRAM in this year's increase and currently catching up. Long term agreements (LTAs) provide support for prices, and due to the fact that major new wafer fabs will not start production until 2028, supply will continue to be tight. In the short term, the performance of various manufacturers may vary due to LTA terms, but in the long run, they will maintain an upward trend. ”
Regarding the future trend, MS Hwang stated that memory prices are expected to remain strong next year. The HBM price, which had previously lagged behind in growth, is catching up with traditional DRAM, and long-term supply agreements are also providing support for the price. In addition, the new wafer fabs of major manufacturers are expected to start production only in 2028, and the tight supply situation may continue.
The massive demand has driven the average selling price of DDR and LPDDR to a historic high, with their revenue increasing by 500% and nearly 400% year-on-year, respectively. We have observed a significant increase in server CPU related memory consumption, which will further push up the average price per Gb next year and put pressure on the end market.
