


STMicroelectronics expects Q4 revenue and gross profit margin to exceed expectations, with AI data center demand as the main driving force
On October 29th, STMicroelectronics released its financial report for the third quarter of 2026 and provided guidance for the fourth quarter that exceeded market expectations, indicating a sustained recovery in chip demand after a long period of sluggishness. The company expects a median net revenue of $4.15 billion (approximately RMB 27.7 billion) for the fourth quarter, a month on month increase of approximately 10.5% and a year-on-year increase of approximately 24.7%, which is higher than the average analyst expectation of $4.11 billion compiled by Bloomberg; The gross profit margin is expected to be 39%, which is also higher than the market's previous estimate of 38.2%.
There is clear demand support behind the guidance exceeding expectations. CEO Jean Marc Chery stated in July this year that revenue growth will accelerate in the fourth quarter, driven by demand for AI data centers and low Earth orbit satellite communications (LEO). The optimistic expectations previously given by the company once made the market doubt - the second quarter financial report released in July fell short of high expectations due to guidance, causing the stock price to plummet by 17%, setting a record for the largest decline in the market in a year.
Q3 financial report revenue exceeded expectations, EPS slightly lower
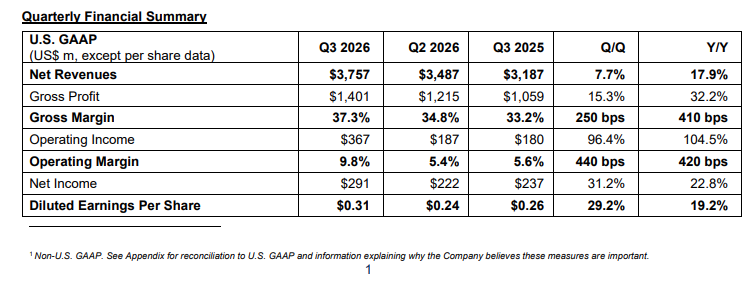
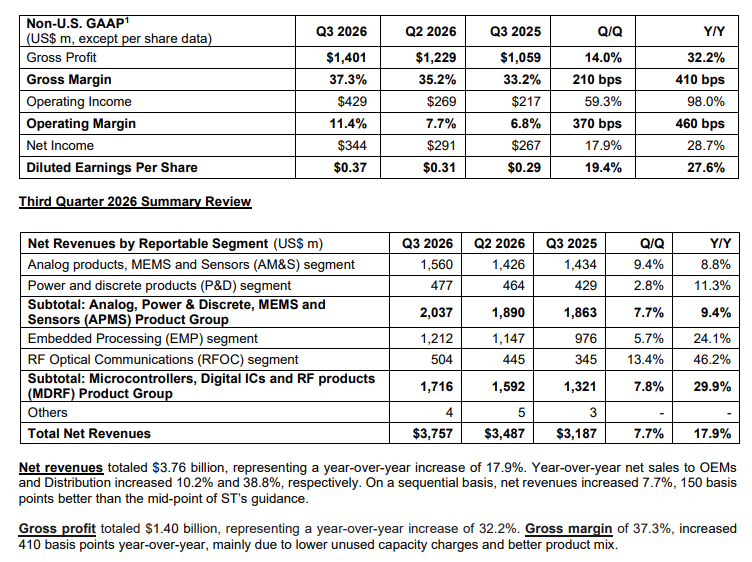
In the third quarter of 2026, the company achieved a revenue of 3.76 billion US dollars, a year-on-year increase of 17.9%, exceeding market expectations; Non GAAP earnings per share were $0.37, slightly lower than market expectations. It is worth noting that the revenue for this quarter exceeded the median guidance of $3.7 billion (± 3.5 percentage points) previously provided by the company, but the year-on-year growth rate slowed down compared to the 26.0% in the second quarter.
Significant improvement in cash flow: net cash flow from operating activities in the third quarter was 1.02 billion US dollars, compared to 549 million US dollars in the same period last year; Net capital expenditure was 643 million US dollars, compared to 401 million US dollars in the same period last year; Free cash flow was positive at $351 million, compared to only $130 million in the same period last year.
The growth engine comes from AI data centers and satellite communication, diversified to hedge against the sluggish automotive market
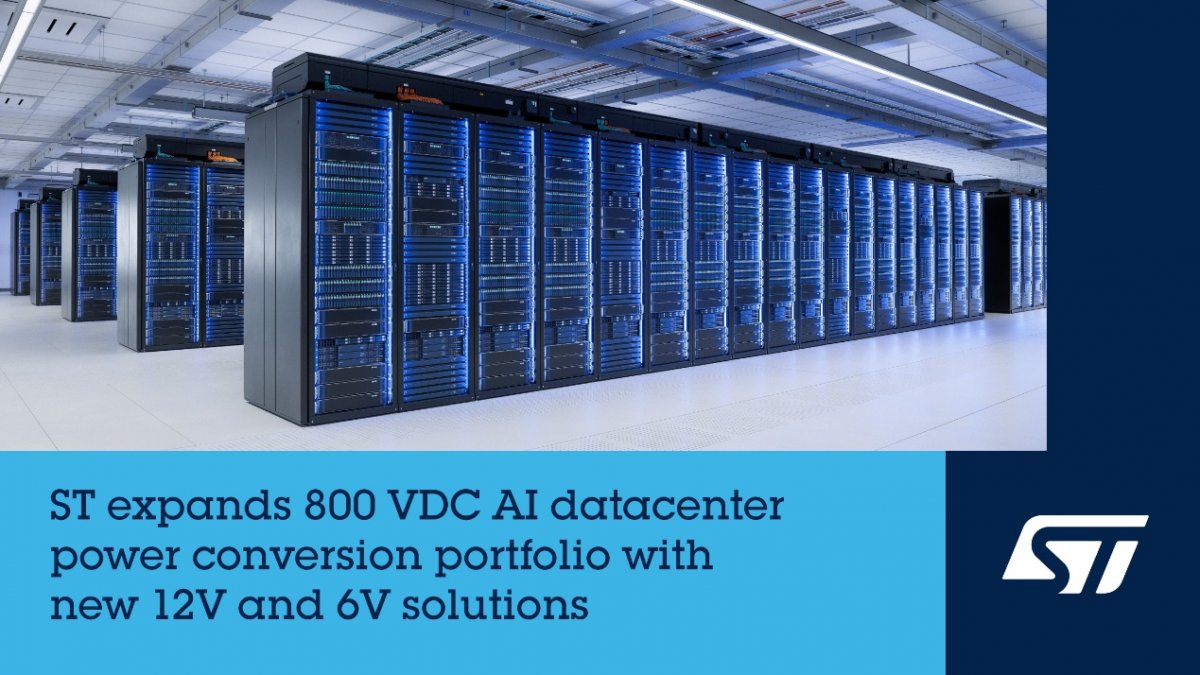
STMicroelectronics' customers include Apple and Tesla. The company is accelerating diversification beyond its core automotive and industrial markets, partnering with European peers such as Infineon to target the demand for power management chips brought about by the construction of AI data centers - chips used to support advanced processors from manufacturers such as Nvidia. The company has raised its data center business target in the second quarter report: data center revenue is expected to exceed $1 billion by 2026, and if the current momentum continues, it is expected to exceed $2 billion by 2027.
Morgan Stanley analyst Sandeep Deshpande and others wrote in a report before the release of the financial report that STMicroelectronics has released signals of confidence in strong AI related orders, "which are expected to support the company's above normal seasonal growth," and expect gross profit margins to improve compared to the previous quarter.
At the industry level, there is also a response: Texas Instruments gave strong revenue guidance last week, stating that demand for industrial, automotive, and data centers is "broadly growing"; However, after its competitor NXP Semiconductors released weaker than expected revenue guidance on Wednesday, its stock price fell, indicating that the market's cautious sentiment towards the semiconductor sector is still present - investors are concerned about the sustainability of massive investments in AI infrastructure and are also wary of competition from Chinese chip manufacturers.
H2 growth rate is expected to exceed normal seasonal levels
According to the company's plan disclosed in July, revenue exceeding $4 billion in the fourth quarter means that the growth in the second half of the year compared to the first half will exceed its normal seasonal level of 15%. The current gross profit margin guidance of 39% has continued to improve compared to the level of about 37% in the third quarter, reflecting an increase in capacity utilization. According to Q2 performance materials, the company's underutilization of capacity expenses has continued to decline from the previous quarterly level of about $100 million, indicating that the boost to profits from the restructuring plan is still being realized.
It should be noted that the company's performance outlook is based on an assumed exchange rate of 1.14 US dollars to 1 euro, and does not take into account the potential impact of further changes in global trade tariffs. Against the backdrop of the automotive chip market gradually emerging from a long-term slump and AI and satellite communication taking over, this guidance of "revenue and gross profit margin exceeding expectations" adds new footnotes to the recovery narrative of European semiconductor giants.
